Lowest Home Loan Interest Rate: Getting a home loan is a major financial commitment. Whether you are purchasing your first home or upgrading to a bigger property, choosing the right home loan interest rate can make a significant difference to your long-term financial planning.
Even a small difference in the interest rate can affect your monthly EMI and the total interest you pay over 15, 20 or 30 years.
However, many borrowers make the mistake of choosing a bank based only on its advertised interest rate. In reality, your CIBIL score, income, employment profile, existing EMIs, property value and repayment capacity can all influence the final home loan offer.
So, how can you get the lowest home loan interest rate in India?
In this guide, we will discuss 10 practical tips to help you compare lenders, negotiate better rates, improve your credit profile and reduce your overall home loan interest.
1. Maintain a Good CIBIL Score Before Applying for a Home Loan
Your CIBIL score is one of the important factors lenders consider when evaluating your home loan application.
A good credit score indicates that you have managed your previous loans and credit card payments responsibly. It can improve your chances of loan approval and may help you qualify for a more competitive home loan interest rate.
Generally, a CIBIL score of 750 or above is considered favourable by many lenders. However, each bank and housing finance company follows its own credit assessment policy.
How Does CIBIL Score Affect Home Loan Interest Rates?
When you apply for a home loan, the lender may evaluate:
- Your CIBIL score and credit history.
- Existing loan repayment behaviour.
- Credit card payment history.
- Outstanding loan obligations.
- Recent credit enquiries.
- Previous loan settlements or defaults.
If your credit profile is strong, you may have better negotiating power.
On the other hand, a low CIBIL score or irregular repayment history may result in a higher interest rate, lower loan eligibility or even rejection.
Tips to Improve Your CIBIL Score
- Pay all your existing EMIs on time.
- Avoid missing credit card payment due dates.
- Keep your credit card utilisation under control.
- Avoid applying for multiple loans unnecessarily.
- Check your credit report regularly.
- Report any incorrect information in your credit report.
Pro Tip: Check your CIBIL report before applying for a home loan. Correcting errors and improving your repayment history in advance may strengthen your loan application.
2. Compare Home Loan Interest Rates from Multiple Banks
One of the best ways to find a competitive home loan interest rate is to compare offers from different banks and housing finance companies.
Never depend entirely on the first bank that contacts you.
Different lenders may offer different interest rates to the same customer because their credit policies, risk assessment methods and pricing strategies may vary.
For example, one bank may offer a lower interest rate to a salaried applicant with a strong credit profile, while another lender may provide a different offer for the same applicant.
What Should You Compare Before Selecting a Home Loan?
Do not compare only the advertised interest rate. Consider these factors:
| Comparison Factor | What to Check |
|---|---|
| Interest Rate | Actual rate offered for your profile |
| Processing Fee | Total loan processing charges |
| Legal Charges | Property legal verification costs |
| Technical Charges | Property valuation expenses |
| Benchmark | External or internal benchmark, as applicable |
| Rate Reset | Frequency of interest rate revision |
| Part Payment | Applicable conditions and charges |
| Customer Service | Loan servicing and support facilities |
You should also request the Key Facts Statement (KFS) and review the Annual Percentage Rate (APR), which helps you understand the overall cost of borrowing.
Important: The lowest advertised home loan interest rate is not necessarily the lowest rate available to you. Always compare the final written offers received from lenders.
3. Negotiate with the Bank for a Lower Home Loan Interest Rate
Many borrowers do not realise that home loan interest rates may be negotiable.
If you have a strong financial profile, you can request the bank to offer a better interest rate.
Your negotiating position may improve if you have:
- A CIBIL score of 750 or above.
- Stable monthly income.
- Good employment or business stability.
- Low existing EMI obligations.
- A healthy repayment history.
- A strong overall financial profile.
How to Negotiate a Better Home Loan Interest Rate
Follow these steps:
- Collect home loan offers from multiple lenders.
- Compare the interest rates offered for your profile.
- Share competing offers with your preferred bank.
- Request a reduction in the applicable interest rate or spread.
- Ask for the revised offer in writing.
- Compare the final charges and loan conditions before accepting.
You can negotiate before accepting the sanction terms, subject to the lender’s policies.
Remember, banks are not obligated to match another lender’s offer. Your final interest rate will depend on the lender’s credit assessment and pricing policy.
4. Understand Repo Rate and External Benchmark-Linked Home Loans
Before selecting a floating-rate home loan, it is important to understand how your lender determines the interest rate.
For new floating-rate retail loans offered by banks, RBI’s external benchmark framework is an important consideration.
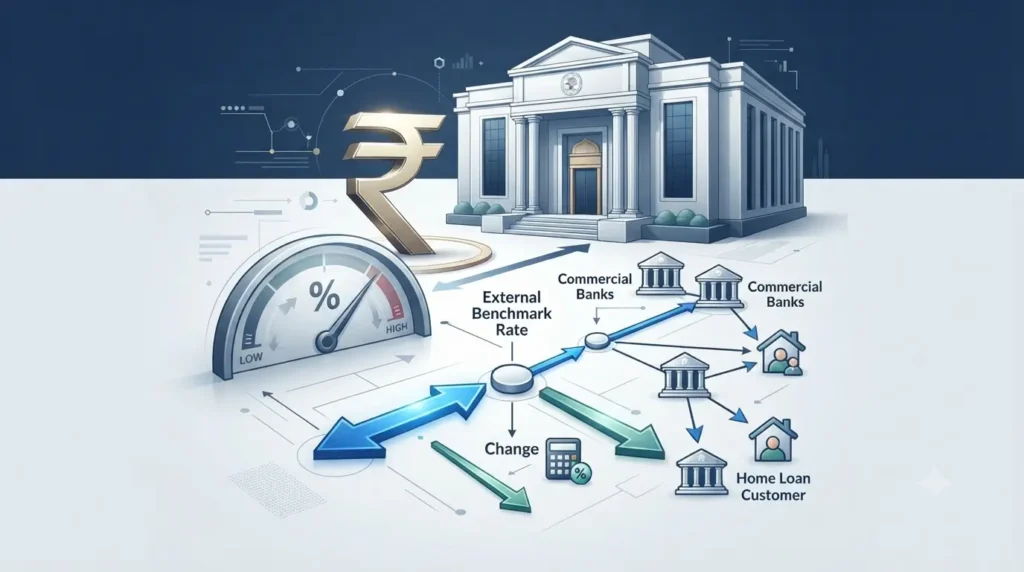
One commonly used external benchmark is the RBI Policy Repo Rate.
What Is a Repo-Linked Home Loan?
A repo-linked home loan is a floating-rate loan whose interest rate is linked to an external benchmark, such as the RBI Policy Repo Rate.
The effective interest rate generally consists of:
Home Loan Interest Rate = External Benchmark + Applicable Spread
For example:
- External Benchmark: 5.50%
- Applicable Spread: 2.50%
- Effective Interest Rate: 8.00%
This is an illustrative example, not a current market offer.
When the external benchmark changes, the lending rate may also change according to the loan agreement and reset terms.
What Is the Difference Between Repo-Linked and MCLR-Linked Loans?
External Benchmark-Linked Lending Rate (EBLR):
The lending rate is linked to an external benchmark, such as the RBI Repo Rate or another permitted benchmark.
Marginal Cost of Funds Based Lending Rate (MCLR):
MCLR is an internal lending benchmark calculated by a bank using specified funding costs and other components.
For new floating-rate retail loans from banks, the external benchmark framework is particularly relevant.
What Should You Check Before Choosing a Floating-Rate Home Loan?
- Which benchmark is used?
- What is the applicable spread?
- How frequently is the interest rate reset?
- What are the conditions for changing the spread?
- How will changes in the benchmark affect your EMI or loan tenure?
An external benchmark-linked loan offers more transparent benchmark transmission, but it does not automatically guarantee the lowest interest rate.
Always compare the complete loan terms.
5. Choose the Right Home Loan Tenure and EMI
Your home loan tenure has a direct impact on your monthly EMI and total interest payable.
A longer loan tenure generally reduces your monthly EMI but increases the total interest paid over the repayment period.
A shorter loan tenure generally increases your EMI but reduces the total interest cost, assuming the interest rate remains unchanged.
Let’s understand this with an example.
Home Loan EMI and Interest Comparison
Suppose you take a home loan of ₹30 lakh at an annual interest rate of 8.65%.
| Loan Details | Scenario 1 | Scenario 2 |
|---|---|---|
| Loan Amount | ₹30,00,000 | ₹30,00,000 |
| Interest Rate | 8.65% | 8.65% |
| Loan Tenure | 30 Years | 20 Years |
| Approx. Monthly EMI | ₹23,387 | ₹26,247 |
| Approx. Total Interest | ₹54.19 Lakh | ₹33.00 Lakh |
<small>Illustrative calculations assuming a constant interest rate throughout the tenure. Actual EMI and repayment figures may vary.</small>
By selecting a 20-year tenure instead of 30 years, the borrower could save approximately ₹21 lakh in interest.
Should You Increase Your Home Loan EMI?
If your monthly income allows you to pay a higher EMI comfortably, you can consider choosing a shorter loan tenure.
However, do not increase your EMI so much that you struggle with household expenses, emergency savings or other financial commitments.
The best loan tenure is one that balances monthly affordability and long-term interest savings.
6. Consider a Home Loan Balance Transfer to Reduce Interest
If you already have an existing home loan at a relatively high interest rate, a home loan balance transfer may help you reduce your borrowing cost.
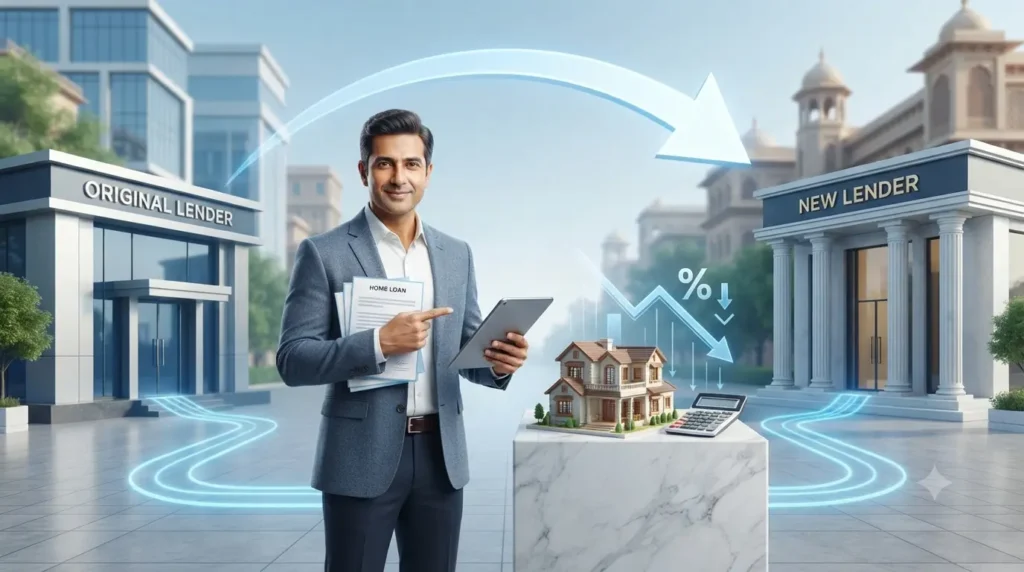
A home loan balance transfer means transferring your outstanding loan from your current lender to another bank or housing finance company offering more favourable terms.
For example:
Suppose your existing home loan interest rate is 9.25%, while another lender offers 8.25% for your eligible profile.
The difference may result in significant savings over the remaining loan tenure.
However, you should not transfer your loan just because another lender advertises a lower interest rate.
When Is a Home Loan Balance Transfer Beneficial?
Consider the following factors:
- Difference between your current and proposed interest rates.
- Outstanding principal amount.
- Remaining loan tenure.
- Processing fees.
- Legal and technical expenses, if applicable.
- Other applicable transfer costs.
- Total interest savings over the remaining tenure.
Calculate Your Actual Savings
Before transferring your home loan, calculate:
Net Savings = Expected Interest Savings − Applicable Transfer Costs
If the savings are meaningful and the new lender offers better overall terms, a balance transfer may be worth considering.
If the interest rate difference is very small, the transfer expenses may reduce or eliminate the financial benefit.
7. Request an Interest Rate Reduction from Your Existing Bank
Before transferring your home loan to another lender, consider contacting your existing bank and requesting an interest rate reduction.
Depending on the lender, this may be called an interest rate conversion, repricing or rate reduction request.
If your repayment history is good and your credit profile has improved, your existing lender may consider reducing your current interest rate.
How to Reduce Your Existing Home Loan Interest Rate
- Check your current home loan interest rate.
- Review your outstanding principal.
- Compare current market offers for a similar borrower profile.
- Contact your existing lender.
- Submit a written request for interest rate reduction.
- Ask about conversion fees and revised loan conditions.
- Compare the revised offer with a balance transfer option.
Sometimes, negotiating with your existing bank can be more convenient than transferring the entire loan to another lender.
However, approval depends on the bank’s pricing policy and your loan profile.
8. Make a Higher Down Payment to Reduce Your Home Loan Amount
Your down payment is another important factor when planning a home purchase.
If you contribute more money from your savings, you may need to borrow less from the bank.
A lower home loan amount can reduce your monthly EMI and total interest payable.
Example: How Down Payment Affects Your Home Loan
Suppose you are purchasing a property worth ₹50 lakh.
| Particulars | Option 1 | Option 2 |
|---|---|---|
| Property Value | ₹50 Lakh | ₹50 Lakh |
| Down Payment | ₹10 Lakh | ₹15 Lakh |
| Home Loan Amount | ₹40 Lakh | ₹35 Lakh |
In Option 2, you borrow ₹5 lakh less.
This can reduce your EMI and total interest payable over the loan tenure.
Why Is a Higher Down Payment Helpful?
- Reduces the principal loan amount.
- Lowers the monthly EMI.
- Reduces total interest payable.
- May improve your loan-to-value ratio.
- Helps manage your long-term financial obligations.
However, do not use all your savings for the down payment.
Keep sufficient funds for stamp duty, registration, property-related expenses, moving costs and emergency savings.
The lender will also determine the eligible loan amount based on applicable loan-to-value limits, property valuation and credit policy.
9. Make Home Loan Part Payments to Save Interest
If you receive additional money through an annual bonus, incentives, business profits or other sources, you can consider making a part-payment towards your home loan.
A home loan part-payment reduces your outstanding principal.
Since interest is calculated on the outstanding principal, reducing the balance can help lower the future interest cost.
For example:
Suppose your outstanding home loan balance is ₹25 lakh.
If you make a part-payment of ₹2 lakh, your outstanding principal may reduce to ₹23 lakh, subject to the lender’s payment adjustment process.
What Happens After a Home Loan Part Payment?
Depending on your lender’s facilities, you may have two options:
Option 1: Reduce Loan Tenure
Keep your EMI approximately the same and reduce the remaining repayment period.
This generally helps maximise interest savings.
Option 2: Reduce Monthly EMI
Keep the remaining loan tenure approximately the same and reduce your monthly EMI.
This can provide additional monthly financial flexibility.
When Should You Make a Home Loan Part Payment?
There is no universal calendar date that is best for every borrower.
The benefit depends on when the payment is credited and how your lender adjusts it against the outstanding principal.
Ask your lender for an updated repayment schedule after making the part-payment.
Important RBI Update: Under the RBI (Pre-payment Charges on Loans) Directions, 2025, effective for loans sanctioned or renewed on or after January 1, 2026, regulated lenders cannot levy prepayment charges on floating-rate loans granted to individuals for non-business purposes. The rules also cover specified other categories. Check the applicable rules for your particular loan.
10. Avoid Borrowing More Than You Actually Need
One common mistake borrowers make is applying for the maximum home loan amount they are eligible for.
Just because a bank is willing to offer you a higher loan amount does not mean you should accept it.
A larger loan generally means:
- Higher monthly EMI.
- Higher total interest payment.
- Greater financial responsibility.
- Less flexibility for savings and investments.
Before applying for a home loan, calculate your actual property requirement.
Consider your:
- Monthly income.
- Existing loan EMIs.
- Household expenses.
- Down payment capacity.
- Future financial goals.
- Emergency savings.
The objective should not be to get the maximum possible loan.
Instead, choose a loan amount that you can comfortably repay without putting unnecessary pressure on your monthly budget.
Important Things to Check Before Finalizing Your Home Loan
Apart from the home loan interest rate, there are several other factors you should review before accepting a loan offer.
| Factor | What You Should Check |
|---|---|
| Interest Rate | Actual rate offered to your profile |
| Benchmark | External benchmark and applicable spread |
| Reset Frequency | How often the interest rate can change |
| Processing Fee | Total processing charges |
| Legal Charges | Property verification expenses |
| Technical Charges | Property valuation expenses |
| Insurance | Whether insurance is optional or required |
| Part Payment | Applicable terms and conditions |
| Foreclosure | Applicable rules and charges |
| Customer Service | Loan servicing and support |
| KFS | APR, applicable fees and repayment schedule |
Always read your sanction letter, Key Facts Statement and loan agreement carefully before accepting the home loan.
Conclusion: How to Get the Lowest Home Loan Interest Rate in India?
Getting the lowest home loan interest rate is not simply about choosing a bank that advertises the cheapest rate.
Your CIBIL score, income profile, existing financial obligations, property details, loan amount and negotiation skills can all influence the final loan offer.
If you are planning to apply for a new home loan, compare multiple lenders, maintain a good credit profile and negotiate before accepting the final offer.
If you already have an existing home loan, review your current interest rate, explore rate reduction options and evaluate whether a home loan balance transfer or part-payment can reduce your overall borrowing cost.
Most importantly, do not borrow more than you actually need.
A well-planned home loan can help you purchase your dream property while keeping your long-term financial commitments under control.
Frequently Asked Questions (FAQs)
1. How can I get the lowest home loan interest rate in India?
Maintain a good CIBIL score, compare different lenders, negotiate the interest rate and choose a suitable loan amount and repayment tenure.
2. What is a good CIBIL score for a home loan?
A CIBIL score of 750 or above is generally considered favourable by many lenders. However, approval and interest rates depend on the lender’s credit policy and your overall financial profile.
3. Can I negotiate my home loan interest rate with the bank?
Yes. You can request a better interest rate before accepting a new home loan offer. Existing borrowers can also request an interest rate reduction from their current lender.
4. How can I reduce my existing home loan interest?
You can explore interest rate reduction options with your existing lender, consider a home loan balance transfer or make part-payments to reduce the outstanding principal.
5. Is a repo-linked home loan better than an MCLR-linked loan?
External benchmark-linked loans provide more transparent benchmark transmission. However, the better option depends on the applicable spread, interest rate, reset terms and overall loan conditions.
6. Does a higher down payment reduce home loan interest?
Yes. A higher down payment reduces the loan amount, which can lower your EMI and total interest payable, assuming the same interest rate and tenure.
7. Is a home loan balance transfer beneficial?
It may be beneficial when the new lender offers a meaningfully lower interest rate and the expected interest savings exceed the applicable transfer costs.
8. Does increasing EMI reduce home loan interest?
Yes. Increasing your EMI can help repay the principal faster, reduce the remaining loan tenure and lower the total interest payable.
9. Is home loan part-payment a good option?
Yes. Part-payment reduces the outstanding principal. If your financial situation allows, reducing the remaining loan tenure can help maximise interest savings.
10. Should I choose the bank offering the lowest advertised home loan interest rate?
Not necessarily. Compare the actual interest rate offered to your profile, APR, processing charges, benchmark, reset conditions and customer service before selecting a lender.
11. Can I get a home loan with a low CIBIL score?
Some lenders may consider applications with lower credit scores, depending on income, repayment capacity and other credit factors. However, approval is not guaranteed and the offered interest rate may be higher.
12. What is the best home loan tenure to save interest?
A shorter tenure generally reduces total interest payable but increases monthly EMI. Choose a tenure that you can comfortably afford while maintaining adequate savings.
Disclaimer: This article is for educational and informational purposes only. Home loan interest rates, eligibility, fees and lending conditions vary by lender and borrower profile. Always verify the latest terms with the relevant bank or housing finance company before making a financial decision.